
Tourism’s role in the European economy is much larger than direct visitor spending alone suggests. New estimates from the European Commission’s Joint Research Centre show that tourism accounts for an average 10.1% of gross value added when its wider impact on suppliers and household spending is included. Its direct contribution stands at 4.1%. This means tourism’s total economic impact is almost two and a half times larger than the value created directly by hotels, restaurants, transport companies and other businesses serving visitors.
The difference comes from the wider chain of economic activity created by tourism. A hotel does not only generate income from selling rooms. It also buys food, energy, technology, cleaning services and other products. Suppliers then generate their own business, while employees working across the tourism economy spend part of their income in other sectors. The new indicator measures these direct, indirect and induced effects together. The Joint Research Centre developed the system using official tourism and economic data, including national Tourism Satellite Accounts and Eurostat figures.
It is the first time the European Commission has published its own estimates of tourism’s total economic impact using the same approach across different European countries. Until now, official EU statistics have focused mainly on tourism’s direct contribution. The findings also show that tourism’s direct share has continued to recover since the pandemic. It stood at 3.6% in 2022 and has now reached 4.1%. For destinations and tourism authorities, the new figures offer a wider way to measure the sector. Visitor arrivals and hotel nights remain important, but the economic value created outside traditional tourism businesses can be much larger than those numbers show.
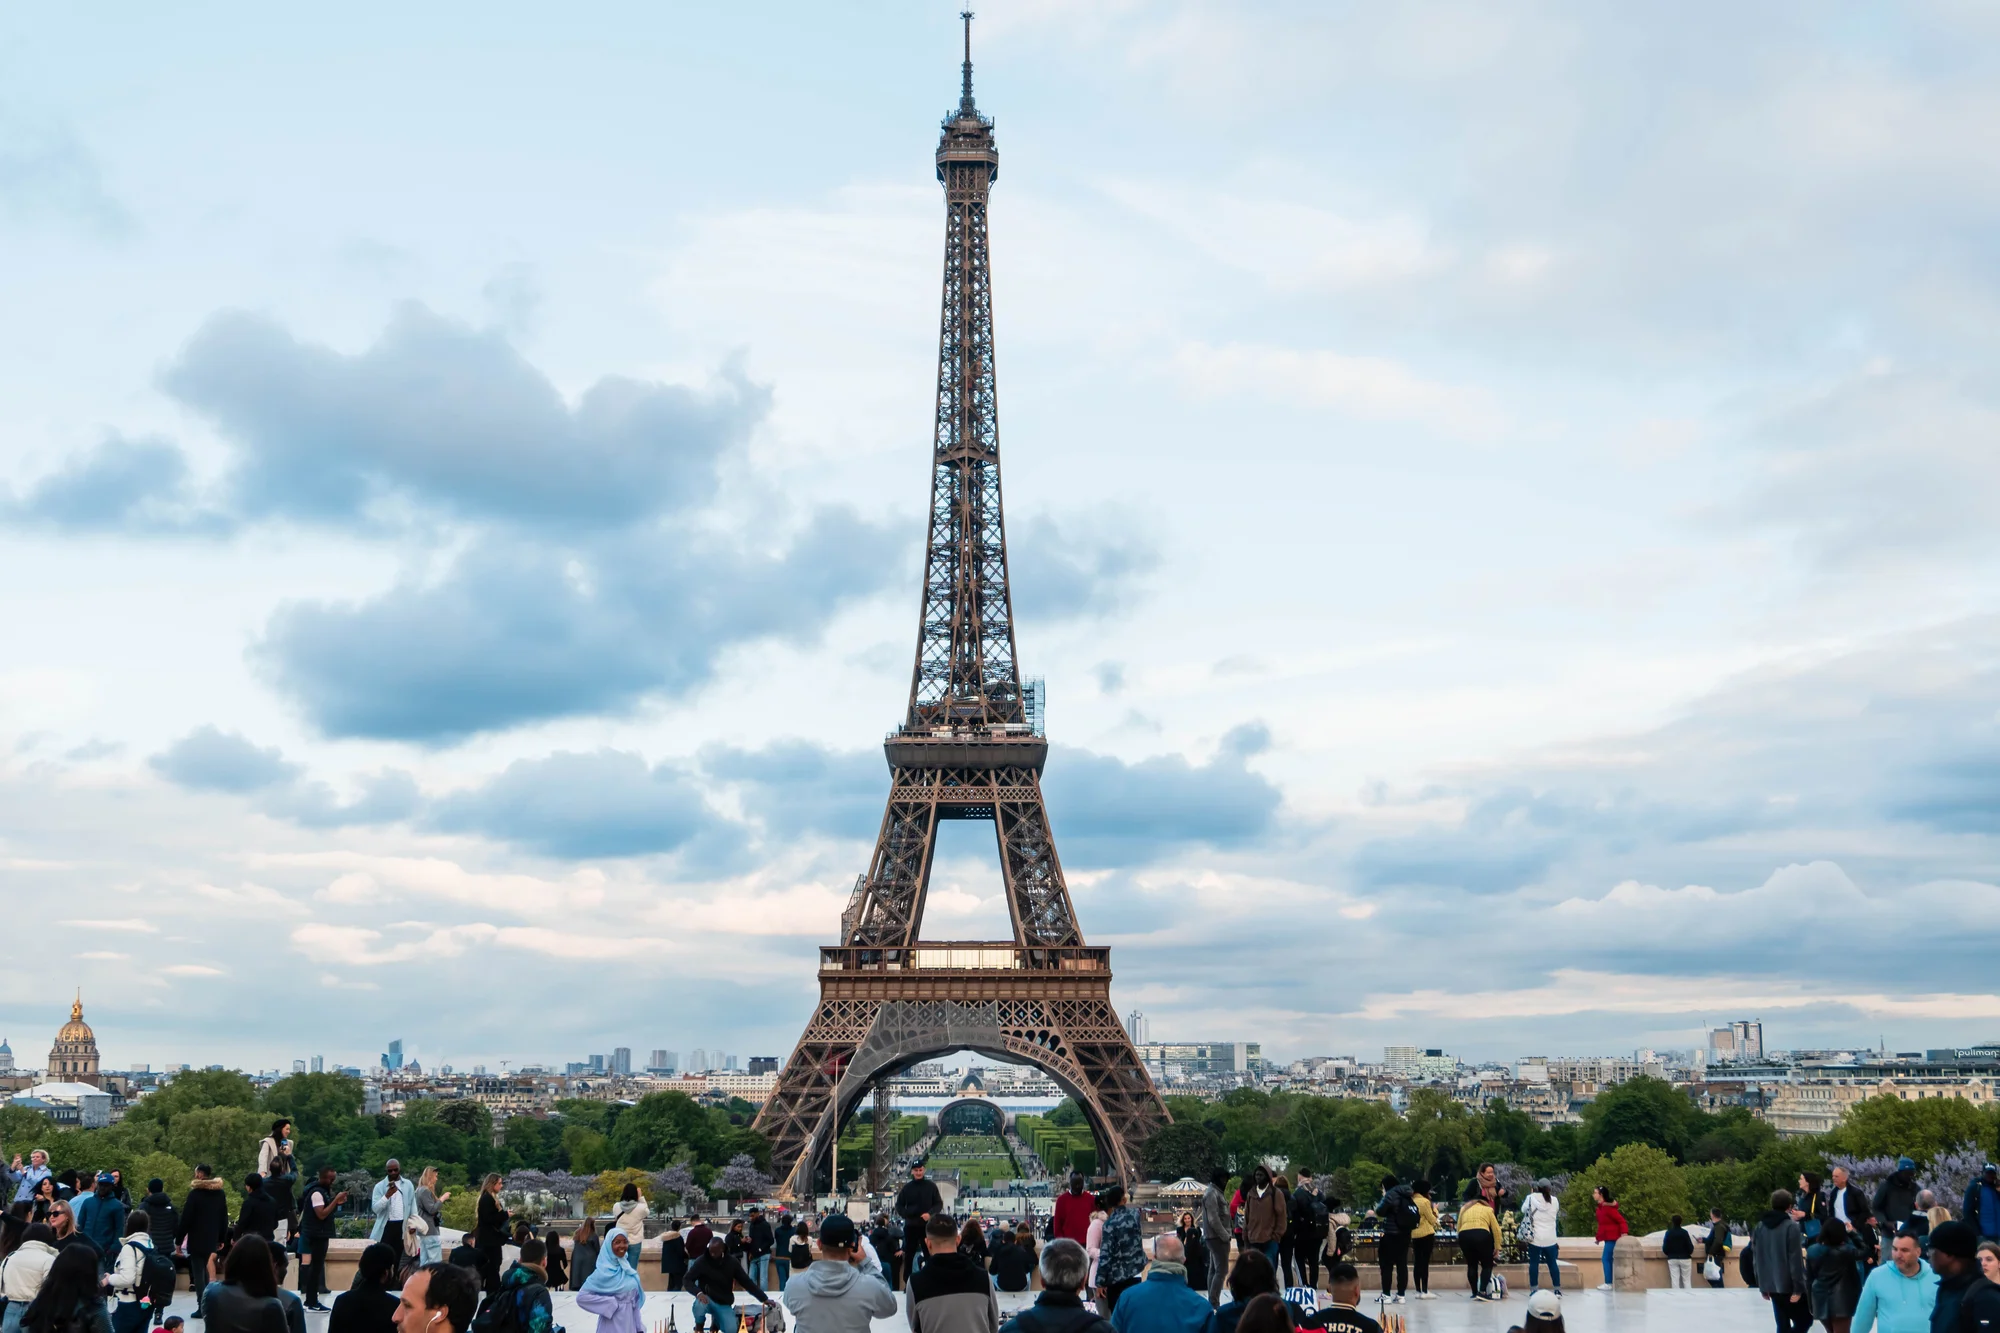
Tourism Accounts For More Than 20% In Portugal And Croatia
Tourism’s economic weight differs sharply across Europe. Portugal and Croatia record the highest levels among the countries highlighted by the European Commission, with tourism’s total impact exceeding 20% of gross value added. In Spain and Italy, two of Europe’s largest tourism markets, the total impact is around 14%. At the other end of the scale, tourism represents slightly less than 5% of gross value added in Belgium and Denmark.
These differences show why tourism policy cannot be viewed in the same way across every European economy. In highly tourism-dependent markets, changes in visitor demand can affect a much wider part of the economy, from food suppliers and transport companies to retail, construction and local services. The same applies to growth. An increase in tourism demand does not only benefit accommodation providers or attractions. It can create additional business for companies supplying the sector and generate more household spending through employment and wages. This wider impact is particularly important when governments assess major tourism investments, destination infrastructure or international events. The return is not always limited to the businesses that deal directly with visitors.
EU Wants A Clearer Picture Of Tourism’s Full Value
Measuring tourism has traditionally been difficult because it is not treated as a single industry in national economic accounts. Tourism activity is spread across many sectors. Hotels are clearly linked to travel, but restaurants, transport providers, retailers and entertainment businesses also serve local residents. Separating visitor spending from normal domestic spending can therefore be complicated.
Tourism Satellite Accounts were created to help solve this problem, but EU-level official statistics have mainly focused on direct economic activity. The new Joint Research Centre method adds the wider supply-chain and household effects. It does this by connecting tourism spending with data showing how different parts of the economy buy goods and services from each other. Accommodation demand is also used to track changes in tourism activity over time. The result gives policymakers a broader view of how visitor spending moves through an economy. This also makes comparisons between countries easier because the same method is applied across the markets included in the analysis.
Tourism Policy Could Move Beyond Visitor Numbers
The new indicator is being introduced as the European Commission puts greater focus on the long-term competitiveness and resilience of tourism. For years, destination performance has often been presented through visitor arrivals, overnight stays and tourism spending. Those figures remain important, but they do not show the full economic value generated by the sector.
A destination attracting high-spending visitors, international congresses or major events may create additional demand across hotels, aviation, local transport, catering, production, retail and professional services. Part of that value can continue moving through the economy after the visitor has left. Understanding this wider effect could become more important when governments decide where to invest public money or how to support tourism during periods of disruption.
It can also change how destinations judge their own performance. More visitors do not automatically mean greater economic value if spending remains limited or does not reach local supply chains. The European Commission’s new approach therefore adds another question to destination strategy: not only how many people visit, but how much economic activity each visitor helps create. For the tourism industry, that could lead to a broader definition of growth. The strongest destinations may not simply be those attracting the highest number of visitors, but those able to spread tourism spending across more businesses, jobs and sectors of the local economy.